IV Macro Policy & Sovereign Debt·Analysis·Europe
Energy's second round shows up on the street, not in wages
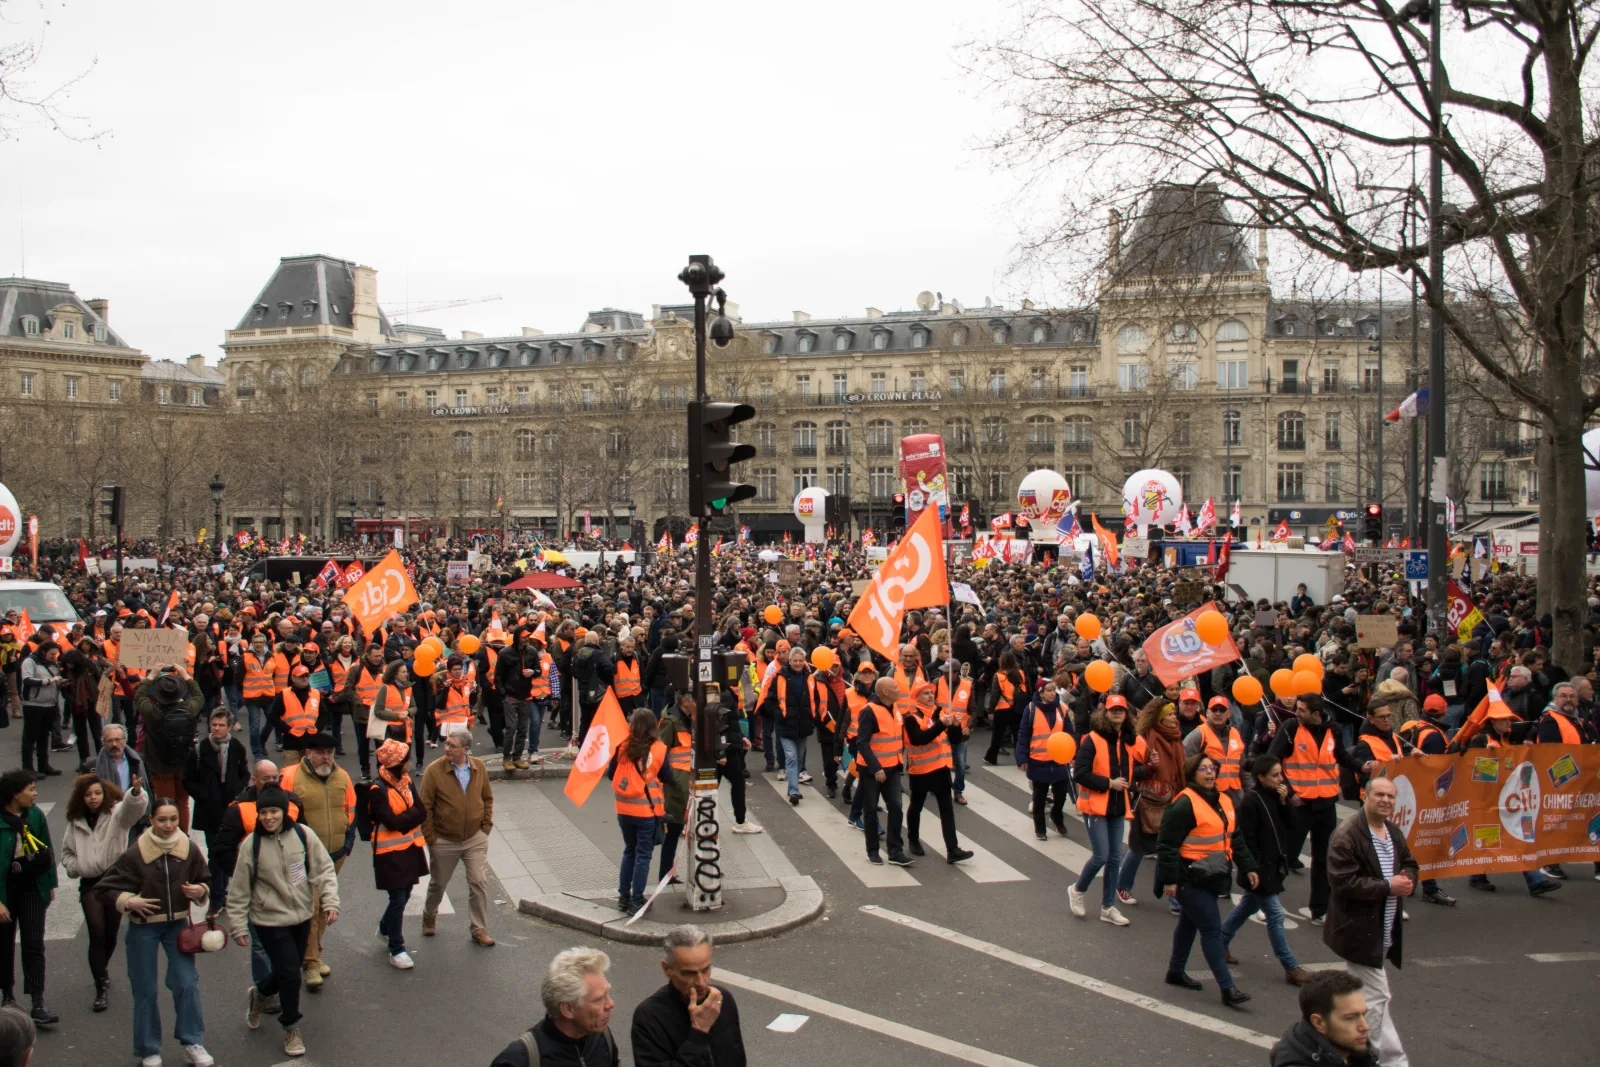
Euro-area inflation ran at 3.8% in September and Italian core at 1.6%, so central banks are hunting the second round in wages. In France 550,000 people marched, the debt premium widened to 142.3 basis points and the bill fell to the fiscal side.
Macro & Debt Markets Desk · 20 October 2026 · 7 min read · 13 sources
Why it matters
Noise: central banks are looking for the second round in wages and not finding it. Lagarde sees no marked wage response, Italian core inflation is 1.6% and Canada's 1.9%. Signal: the energy shock reached politics without passing through pay. Around 550,000 people marched in France on 17 October and detentions passed 2,330. The OAT-Bund spread widened to 142.3 basis points on 19 October, and Milan followed 270 detentions with a decision to deploy 500 soldiers. The constraint is not debt arithmetic but the political capacity to carry a €54 billion adjustment.
Implications
- The French 10-year yield reached 4.85% on 19 October and the spread over German bunds 142.3 basis points; the gap had narrowed to 59 basis points at one point over the past year.
- Italian inflation rose to 4.2% in September, the highest since September 2023, with diesel up 34.9%; the core rate stayed at 1.6%.
- Moody's reviews France's Aa3 rating with a negative outlook on 23 October; the agency will look at whether political institutions can produce policy despite a hung parliament.
Noise
The energy shock stays temporary because no second round is visible in wages.
Signal
The debt premium is pricing political capacity.
Noise in wages, signal on the street
The question the market is asking this week is whether the energy shock has passed into wages. On Newsquawk's 19 October compilation, Lagarde said euro-area September inflation had risen to 3.8% on energy but that there was no marked response in wages. The ECB raised rates by 25 basis points in June and again in September, and meets next on 29 October. The second-round effect — energy prices spreading into wages and service prices — is being read as the axis of that decision.
That reading is noise. CBS News reports that officials counted roughly 550,000 marchers in France on 17 October over the cost of living and school conditions; Al Jazeera puts weekend detentions above 2,330. The same weekend brought roughly 270 detentions in Milan, with the unrest spreading to Bologna and Turin. The signal sits here. The second round of this energy shock is appearing in the streets and in parliament before it reaches a wage contract, and the bill is being paid by finance ministries rather than central banks.
Headline high, core low
The picture is the same on both sides of the Atlantic. According to Il Sole 24 Ore, Italian September inflation rose to 4.2% with diesel up 34.9%, while the core rate stayed at 1.6%. Canadian headline inflation climbed to 3.1% as the central bank's core measures eased to 1.8-1.9%. In the United States September CPI was 3.7% and core CPI 2.6%.
The gap between headline and core is 2.6 points in Italy, 1.2 in Canada and 1.1 in the US. For a central bank that gap is a reason to wait; BMO's chief economist Douglas Porter said the Canadian data did not strengthen the case for a hike. For a household the same gap is a direct loss of income, because people who spend most of what they earn on fuel and transport take no comfort from a 1.6% core rate. The wider the gap, the wider the distance between a central bank's patience and the street's.
The global rate environment is narrowing the fiscal space too. FXStreet reports that the US 10-year yield rose 6 basis points to 5.144% on 19 October as oil returned to $99. The market prices the probability of a December Fed hike at roughly 92%, and Barclays expects a second rise in January. Paris therefore has to finance every concession it makes by borrowing at 4.85%. Allianz Trade calculates that a 100 basis-point rise in rates adds roughly €25 billion of gross interest cost for French households, companies and the state within three to six months.
The constraint is political capacity, not debt arithmetic
France is paying for that gap in its bond market. Ideal-Investisseur data put the French 10-year yield at 4.85% on 19 October and the spread over bunds at 142.3 basis points. The government's 2027 budget aims to cut the deficit from 5.4% of GDP to 5%, an adjustment of roughly €54 billion. NosParlementaires reports that only 7 of the 58 articles on the revenue side have been debated, with more than 2,800 amendments pending.
Allianz Trade puts the deficit needed to stabilise the debt at 2.7% of GDP, which means savings of more than €80 billion. In an environment where the street is resisting even €54 billion, that number looks politically unbearable. Moody's will measure exactly this on 23 October: whether institutions can produce policy despite a hung parliament. On Selectra's account, Moody's is the only one of the three major agencies still holding France in the Aa category.
In Italy the Meloni government is preparing a security answer on 20 October, with 500 soldiers and a decree allowing preventive detention. That answer may suppress the unrest, but it does nothing about the 25.8% rise in regulated energy prices. The second stage will most likely be demands for energy support, which would push both of the euro area's large debtors to loosen fiscally at the same time. Allianz Trade notes that the ECB's emergency protection instrument can only be deployed in a political crisis where the spread passes 200 basis points.
What would refute this reading
Our thesis is this. Over the next three months the sovereign debt premium in the euro area will be set less by core inflation than by political resistance to the cost of living. The OAT-Bund spread will stay in a 120-150 basis-point band. We put 55% on that path.
First refutation: if the revenue side passes parliament without concessions and the spread falls below 120 basis points within two weeks, the political capacity problem has been overstated. Second refutation: if euro-area core inflation jumps in October and the ECB hikes on 29 October, the constraint reverts to monetary policy. Third refutation: if the December Brent contract settles durably below $100, the gap between headline and core closes and the pressure on the street weakens.
Probabilities
Scenarios
| Scenario | Probability | Trigger | Market impact |
|---|---|---|---|
| H1Watered-down consolidation | 55% | The French budget passes with concessions or under article 49.3, Moody's holds the rating or leaves the outlook unchanged, and the protests subside. | The deficit target slips above 5%, the OAT-Bund spread stays high in a 120-150 basis-point band and the ECB keeps waiting. |
| H2Street and rating together | 30% | Moody's cuts the rating to A1 on 23 October, protests extend into another weekend and curfews arrive in Italy. | The French spread passes 150 basis points and carries into Italy, governments increase energy support and deficits widen. |
| H3An oil retreat closes the gap | 15% | An interim arrangement is reached at Hormuz and the December Brent contract settles durably below $100. | Headline inflation converges on core, street pressure and demands for energy support ease, and budget bargaining gets easier. |
Module A
Constraints Matrix
STRUCTURAL AVG 4.0 · TACTICAL AVG 3.0Structural constraints dominate: the outcome is set more by these limits than by the actors' preferences.
Hard structural constraintspersistent · beyond the actors' will
Hung parliament
5/5Only 7 of the 58 articles on the revenue side of France's 2027 budget have been debated and more than 2,800 amendments are pending; the committee had rejected the revenue side by 31 votes to 3.
Headline-core gap
4/5Italian headline inflation is 4.2% against core of 1.6%; in Canada 3.1% against 1.9%, in the US 3.7% against 2.6%. Central banks watch core and wait while households pay the headline.
Debt stabilisation threshold
4/5Allianz Trade puts the deficit needed to stabilise French debt at 2.7% of GDP, requiring savings of more than €80 billion; the government's target is 5%.
The ECB is not a rescuer · European Union
3/5Allianz Trade notes that the ECB's protection instrument can only be deployed in a political crisis where the spread passes 200 basis points; the ECB raised rates by 25 basis points in June and in September.
Tactical frictiontemporary · eases over time
Moody's review days
4/5Moody's reviews France's Aa3 rating with a negative outlook on 23 October; the possible outcomes are holding the rating, a cut to A1 or a change of outlook.
Fresh protest call weeks
3/5Al Jazeera reports that the gilets jaunes have called for demonstrations next weekend; the government declared curfews in Paris, Lyon, Nice and Lille on 19 October.
Italian security decree days
2/5The cabinet is discussing a decree on 20 October covering 500 soldiers and preventive detention for minors; approval could not be confirmed at the time of writing.
Module B
Signal vs Noise
SIGNAL 60% · NOISE 40%
- NOISE
The energy shock stays temporary because no second round is visible in wages.
Lagarde said euro-area September inflation had risen to 3.8% on energy and that there was no marked response in wages; the ECB forecasts growth of 0.9% for 2026.
- SIGNAL
The debt premium is pricing political capacity.
The OAT-Bund spread was 137.4 basis points on 16 October and 142.3 on 19 October after the protests and curfews; the low of the past year was 59 basis points.
- SIGNAL
Price pressure is crushing household budgets without spreading to core.
Italian September inflation was 4.2%, regulated energy up 25.8% and diesel up 34.9%, while the core rate stood at 1.6%.
Il Sole 24 Ore — Istat confirms that inflation jumped to 4.2 per cent in September
- NOISE
The violence in France is a migration-driven security problem.
French officials attribute the violence to far-left groups and opportunistic looters; the demands of the 550,000-strong march were the cost of living and school conditions.
CBS News — French police arrest more than 1,800 people after violent protests erupt across country
- SIGNAL
A rating agency will measure political capacity directly.
Moody's reviews France's Aa3 rating on 23 October; Fitch and S&P hold the rating at A+.
Module C
Asset-Class and Positioning Implications
| Asset class | Exposure | Transmission channel | H1 | H2 | H3 | Expected | Conviction | Horizon | What to watch |
|---|---|---|---|---|---|---|---|---|---|
| Sovereign debt | Euro-area periphery bonds | Cost-of-living protests weakening fiscal consolidation | − | −− | + | −1.00 | ●●● | 0–3 months | The 150 basis-point threshold for the OAT-Bund spread |
| Sovereign debt | German government bonds | Haven demand from money leaving periphery risk | + | ++ | − | +1.00 | ●●● | 0–3 months | Any deviation of the German 10-year yield from 3.42% |
| FX | Euro-dollar | Euro-area political risk and the pricing of a December Fed hike | − | −− | + | −1.00 | ●●● | 0–3 months | The 1.10 threshold for the euro against the dollar |
| Volatility | European equity volatility | A rating downgrade and spreading protests | 0 | ++ | − | +0.45 | ●●● | 0–3 months | Moody's decision on 23 October and weekend demonstrations |
| Credit | European consumer-facing corporate credit | The energy bill squeezing household spending | − | −− | + | −1.00 | ●●● | 3–12 months | The euro-area flash services PMI |
Second-order effects
And then what?
Starting point
Energy prices lifted euro-area September inflation to 3.8% and Italy's to 4.2%; with the core rate at 1.6%, 550,000 people marched in France and 270 were detained in Milan.
- 1
Budgetwithin weeks
After the security measures, governments turn to cost-of-living concessions; France's €54 billion adjustment is watered down, energy support returns to the agenda in Italy and deficit targets slip.
Watch: The vote on the revenue side of France's 2027 budget and the Italian cabinet's decisions on energy support
- 2
Sovereign debt premiumwithin weeks
Rating agencies and the bond market price political capacity; if Moody's downgrades, the French spread passes 150 basis points and the move carries into Italian bonds.
Watch: Moody's decision on 23 October and the 150 basis-point threshold for the OAT-Bund spread
- 3
External demand and cost of capitalwithin months
Rising borrowing costs weaken euro-area demand; neighbouring economies that use the EU as their main export market, Türkiye among them, see pressure on orders and on external funding costs.
Watch: Exports to the EU in TurkStat's monthly trade data and euro-area flash PMIs
What breaks the chain
A durable fall in the December Brent contract below $100 would pull headline inflation down and weaken street pressure; if the French budget passes without concessions, the rating channel stops at the first step.
Triggers
Thresholds to watch
| Indicator | Threshold | Today | What it means |
|---|---|---|---|
| EUR/USD | < 1.10 | 1.1253 | A fall in the euro from 1.1230 on 19 October to below 1.10 would show the market carrying political risk in France and Italy into the currency itself. |
| Brent crude oil (futures) | < $100 | 109.55 | A durable fall in the December Brent contract below $100 would close the gap between headline and core inflation and cut the fuel for street pressure. |
Sources
- Newsquawk — Daily European Opening News, 19th October 2026
- Ideal-Investisseur — OAT / Bund spread
- CBS News — French police arrest more than 1,800 people after violent protests erupt across country
- Al Jazeera — France announces curfews in aftermath of violent protests
- Il Sole 24 Ore — Istat confirms that inflation jumped to 4.2 per cent in September
- Statistics Canada — The Daily, Consumer Price Index, September 2026
- BNN Bloomberg — Higher gas prices drove inflation up to 3.1% in September: StatCan
- Chase — Will the Fed hike rates in October?
- NosParlementaires — Budget 2027 vote date: Tuesday 20 October, with the text unfinished
- Allianz Trade — Toasted, not burnt: France's bond sell-off and the road to the 2027 election
- Selectra — Moody's to review France's rating on 23 October
- ProtoThema English — Italy to deploy 500 troops to Milan amid violent unrest
- FXStreet — Gold sags near $4,150 as Oil fuels US yields rebound
Sourcing and verification rules: methodology · Report an error: contact
Related reports
IVMacro & Debt·Analysis·Americas
Interest is now the main engine of the US deficit
The US closed fiscal 2026 with a 1.992 trillion dollar deficit, and two-thirds of its growth came from interest. The average rate on the debt is 3.53% against a 10-year yield of 5.09%; as that gap closes, the bill grows regardless of what the Fed decides.
Macro & Debt Markets Desk · 18 October 2026 · 9 min
IVMacro & Debt·Analysis·Americas
Central banks pause in October as energy persistence decides December
The Fed, the ECB, the Bank of England and the Bank of Canada are reacting to the same energy shock at different speeds. Markets price a pause at the 28–29 October meetings. The real decision rests on November data showing whether energy has reached services prices.
Macro & Debt Markets Desk · 17 October 2026 · 9 min
IVMacro & Debt·Analysis·Türkiye and Its Neighbourhood
MSCI's freeze leaves Turkish rate cuts leaning on bond money
On 15 October MSCI froze weight increases and new stock additions in its Türkiye indices. Foreign ownership rose to 36.93% in September, yet index weight cannot follow. The 36% decision expected on 22 October must now weigh the carry trade in bonds, the only door still open.
Türkiye & Neighbourhood Desk · 17 October 2026 · 8 min