I Geo-Economics & Chokepoints·In-depth analysis·Türkiye and Its Neighbourhood
From a struck distillation unit to 100-lira diesel: Russian refinery capacity and Türkiye's three-channel bill
Ukrainian drones are cutting Russian refinery capacity, Moscow is closing exports and Türkiye is losing half its cargo allocation. But the 100 lira at the pump is the sum not of one shock but of three separate channels.
Türkiye & Neighbourhood Desk · 18 September 2026 · 12 min read · 11 sources
Why it matters
Russia extended the diesel export ban to 31 October and widened it to all producers; three of its six large diesel refineries are curtailed and exports fell below 1 million tonnes in June. Türkiye lost at least 50% of its previous cargo allocation and diesel passed 100 lira for the first time on 17 September. The price contains a dollar rate of 48.67 lira and successive excise rises as much as it contains cargo scarcity; that third channel brings Türkiye face to face with its own fiscal repair.
Implications
- Russian diesel exports fell below 1 million metric tonnes in June, against roughly 2.5 million tonnes a month a year earlier; Türkiye and Brazil lost at least 50% of their previous cargo allocations.
- Diesel passed 100 lira for the first time in Türkiye's history on 17 September; it was the third increase in a row and a combination of cargo scarcity, a dollar rate of 48.67 lira and excise rises, not crude oil alone.
- As the eight-month budget deficit reached 1,308.1 billion lira, interest payments rose 39.4%; fuel taxation serves at once as an instrument of fiscal repair and as a source of inflation.
The head of the chain: two of three primary distillation units out of service
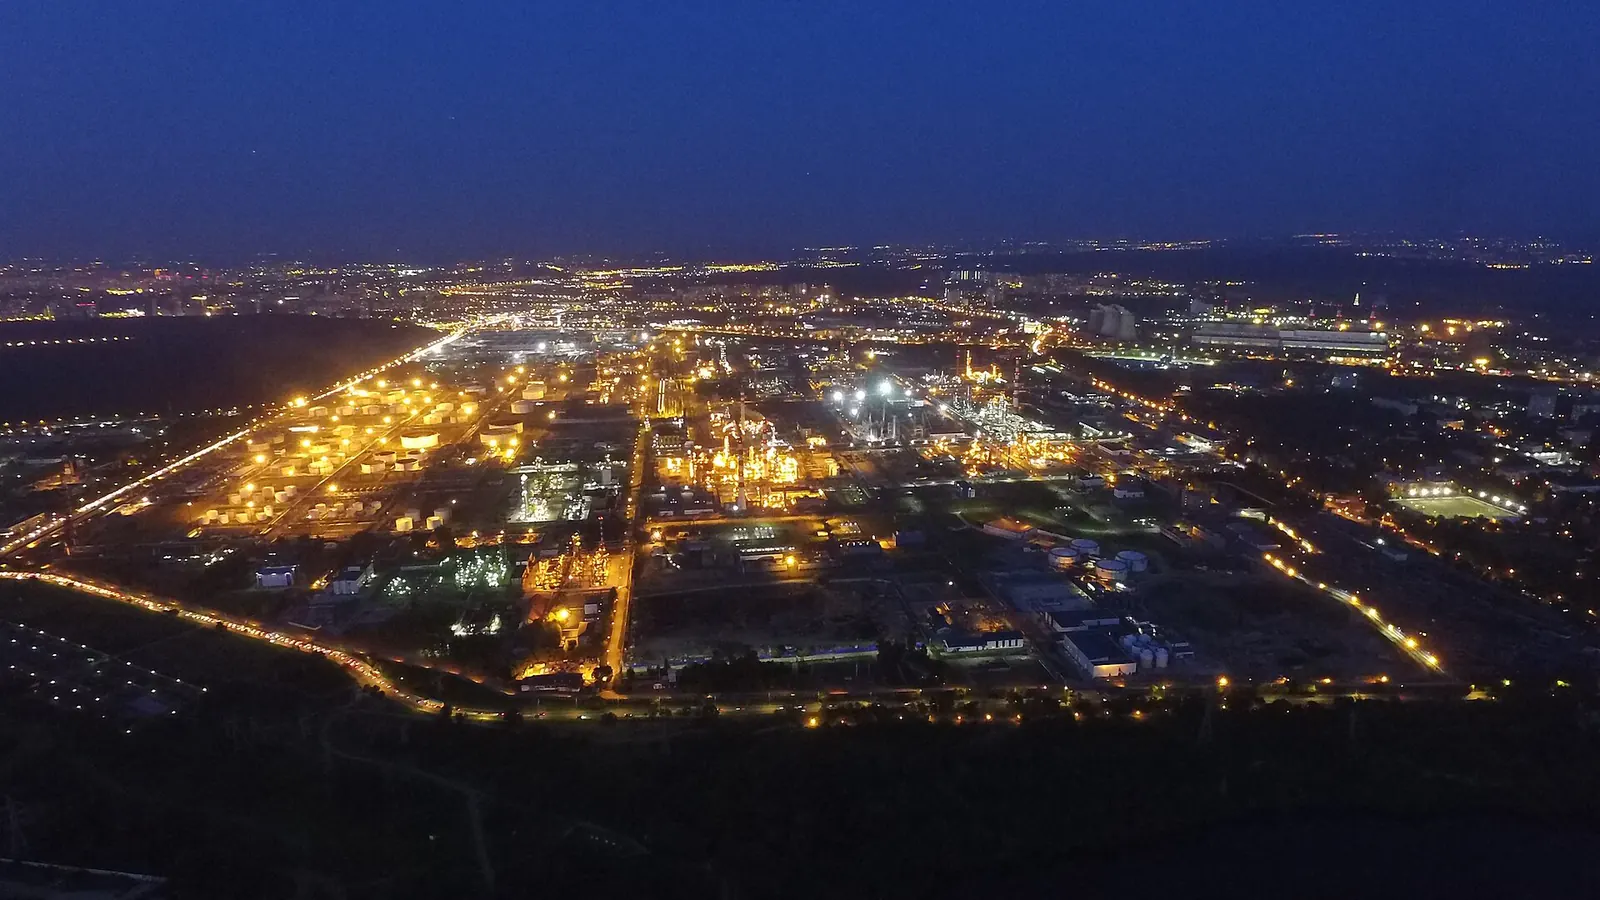
On the night of 16-17 September Ukrainian drones struck the Slavneft-YANOS refinery 250 kilometres north-east of Moscow. According to United24 Media, the unit hit was the AVT-3 primary distillation unit with a capacity of 17,140 metric tonnes a day, corresponding to about 40% of the capacity of a plant that processes roughly 15 million tonnes of crude oil a year. According to the same source, the AVT-4 unit, with a capacity of 14,300 tonnes a day, had already been under repair since the attack of 28 August. In other words, two of the plant's three primary distillation units are out of service at the same time.
This is not one plant's problem. According to OilPrice's breakdown of 16 September, Kirishi is entirely out of service, Volgograd and NORSI are running at about 25% capacity, and Taneco has been struck. These three plants correspond to roughly half of Russia's diesel output. That three of Russia's six large diesel-producing refineries severely curtailed or entirely halted output in September shows that the capacity loss is no longer an isolated damage item but a systemic supply constraint.
Sources conflict on the scale of the attack, and the conflict is worth noting. Kyiv Post reported that Russian officials claimed 65 drones had been shot down during the attack, while The Moscow Times wrote that the Russian defence ministry announced it had intercepted 641 drones across Russia and Crimea between Wednesday night and Thursday morning. The Ukrainian side's claim that it destroyed 1 An-12, 2 An-26 and 3 helicopters at the Tsentralny military airfield in Rostov-on-Don could not be independently verified. Yaroslavl's governor Mikhail Yevrayev said the fire at the refinery had been fully extinguished by Thursday morning; there is no announced timetable for repairs.
The export ban is not a supply decision but an admission of scarcity
According to Hydrocarbon Processing, the diesel export ban due to expire on 30 September was extended to 31 October at a meeting chaired by Deputy Prime Minister Alexander Novak, who handles Russia's oil file. The official justification is deferred refinery maintenance and pre-winter stock replenishment. But the scope of the decision says more than the justification: while in July the ban covered only traders and small refineries, the extended ban covers all producers. Novak's office did not respond to a request for comment and the government did not formally announce the extension.
An export ban widening from traders to producers means an acceptance of giving up the export margin in order to protect the domestic market. Domestic prices support that reading: at the start of September a tonne of diesel rose to 70,546 roubles on the St Petersburg commodity exchange, on 7 September the pump price reached 88.44 roubles a litre, and the increase since the start of the year has reached 18.4%. In other words, Moscow is prioritising price stability at home rather than export revenue.
The loss on the export side is concrete. Russia's diesel exports fell below 1 million metric tonnes in June; a year earlier they were roughly 2.5 million tonnes a month. According to OilPrice, Türkiye and Brazil lost at least 50% of their previous cargo allocations. Because these two countries are among the largest buyers of Russian diesel, the first-order effect of the constraint is seen directly in Mediterranean and Atlantic product flows. For Türkiye this is a question of substituting a supplier before it is a question of price: the lost tonnage has to be covered from another source, most probably over a greater shipping distance.
Transmission to Türkiye: cargo, exchange rate and tax at once
With the increase that took effect at midnight on 17 September, the litre price of diesel passed 100 lira for the first time in Türkiye's history. The sources diverge on the size of the increase: Cumhuriyet wrote that 4 lira 80 kuruş had been added per litre, while Habertürk gave the rise as 4.62 lira. There are small differences in the prices too. According to Cumhuriyet, diesel cost 100.40 lira on the European side of Istanbul, 101.50 lira in Ankara and 101.80 lira in İzmir; Habertürk reported 100.31, 101.43 and 101.70 lira respectively for the same day. Petrol traded in a band of 80.20-81.60 lira and LPG at 34.39-35.09 lira.
This was the third increase in a row: according to Habertürk, 3.20 lira had been added to petrol on 12 September and about 6.5 lira to diesel on 15 September. What matters most is the composition of the price. Cumhuriyet listed the causes of the increase as swings in global markets, movement in the exchange rate and successive excise rises. The exchange rate leg is measurable: according to BloombergHT data, the dollar/lira rate traded at 48.6723 lira at 09.30 on 17 September, roughly 13.12% above the 43.0312 lira at the start of the year. The lira cost of imported fuel has risen by that much even if the dollar price of the product has not changed at all.
Türkiye is therefore taking the same shock through three separate channels at once. The first channel is physical: the loss of at least half of the Russian cargo allocation means substitute supply and longer shipping. The second channel is monetary: the 13.12% rise in the exchange rate makes the same barrel more expensive. The third channel is fiscal: excise rises are loaded directly on top of the price. Though the three look independent of one another, they are derivatives of the same external shock; the exchange rate pressure is itself fed in part by the growth of the energy bill.
One caveat: none of the sources consulted states which crude oil price level is reflected in this increase. How much of the rise at the pump is product premium, how much exchange rate and how much tax therefore cannot be separated out with publicly available data, and could not be independently verified. The impossibility of that separation allows all three sides in the public debate to defend their own account.
Why the pump price is a fiscal matter
Budget data show why the third channel matters so much. According to figures published by the Ministry of Treasury and Finance on 16 September, the central government budget posted a surplus of 12.9 billion lira in August, with revenue of 1,654.9 billion lira and expenditure of 1,642.1 billion lira; Ekonomist gave the same figure as 12.8 billion lira, the difference stemming from rounding. The primary budget surplus in August was 209.9 billion lira.
The monthly surplus does not change the picture. In the January-August period budget expenditure reached 12,162.7 billion lira and revenue 10,854.7 billion lira, leaving a deficit of 1,308.1 billion lira. The eight-month primary surplus is 680 billion lira. The pace of increase in expenditure exceeds that of revenue: according to Ekonomist, eight-month expenditure rose 36.8% and revenue 36%; personnel spending rose 42.7% to 3,385.39 billion lira and interest payments rose 39.4%, approaching 2 trillion lira.
What follows is a vicious circle specific to Türkiye. In a budget where interest payments have risen 39.4%, the fastest instrument for protecting the primary surplus is indirect taxation, and fuel excise is the most flexible of those instruments: collection is immediate, the base is broad, and no legislative process is required. But that very instrument pushes up the most visible item in headline inflation. The 35.7% growth in tax revenue, with income tax up 51.8% and corporation tax up 46.9%, shows that this collection pressure is general.
Türkiye's fiscal repair and its disinflation programme therefore pass over the same pump. When the external shock arrives on the cargo side, the fastest fiscal instrument in the Treasury's hands and the price path targeted by the central bank are pulled in opposite directions. This is not a policy error but a constraint: protecting one of the two objectives requires conceding on the other, and as long as energy prices stay high the gap does not narrow.
The market leg and the unknowns
The financial leg of the shock was seen in the same week. The BIST 100 index closed on 16 September at 13,122.58 points, down 769.72 points or 5.54%; according to Takvim, trading volume was 262 billion lira, the banking index fell 6.38%, the holding index 6.48% and the leasing and factoring index 9.74%, and 17 stocks hit their lower limit. The index fluctuated between 12,817 and 13,877 points during the day; it was the third consecutive day of decline. 17 September opened down 1.32% at 12,948.83 points.
The trigger was not only local: on 16 September the US Federal Reserve raised its policy rate by 25 basis points to the 3.75-4.00% range. The dollar/lira rate closed the day at 48.6520 lira and the euro reached 55.8063 lira. In an environment of rising global rates, the risk premium of an energy-importing economy can rise independently of domestic policy decisions as well; that is an external constraint narrowing the local decision-maker's room for manoeuvre.
There are three things this report does not know. First, the repair time for the AVT-3 unit that was hit; second, whether the ban will genuinely be lifted on 31 October, since the ban itself was never formally announced; third, from which sources and at what shipping cost the Russian cargo allocation Türkiye has lost is being substituted. Until these three unknowns are resolved, there is no data-based answer to the question of whether the increase at the pump is permanent or temporary. The single indicator to watch is not crude oil itself but the path of the Mediterranean diesel product premium, stripped of the exchange rate and tax effects.
Probabilities
Scenarios
| Scenario | Probability | Trigger | Market impact |
|---|---|---|---|
| H1Scarcity becomes permanent | 50% | Repairs to AVT-3 and AVT-4 drag on, capacity does not return at the other plants struck, and the ban is carried beyond 31 October. | The Mediterranean diesel product premium stays high; Türkiye covers substitute cargo over a greater shipping distance and pump increases continue at intervals. |
| H2Gradual normalisation | 30% | Repairs progress, the tempo of attacks falls and the ban ends on 31 October without extension. | The Russian cargo allocation partly returns, exports rise above the threshold of 1 million tonnes a month and the product premium begins to fall. |
| H3A second shock wave | 20% | New deep strikes interrupt the remaining primary distillation capacity, or exchange rate pressure passes the 50 lira threshold. | Physical supply and the lira cost deteriorate at the same time; the intervals between increases narrow and competition for substitute supply hardens. |
Module A
Constraints Matrix
STRUCTURAL AVG 4.3 · TACTICAL AVG 3.0Structural constraints dominate: the outcome is set more by these limits than by the actors' preferences.
Hard structural constraintspersistent · beyond the actors' will
Physical loss of primary distillation capacity · Russia
5/5At YANOS the AVT-3 unit of 17,140 tonnes a day and the AVT-4 unit of 14,300 tonnes a day are out of service at the same time; Kirishi is entirely closed and Volgograd and NORSI are at about 25% capacity.
Türkiye's position as a product importer · Türkiye
4/5As one of the largest buyers of Russian diesel, Türkiye lost at least 50% of its previous cargo allocation; substitute supply requires a greater shipping distance.
Exchange rate pass-through · Türkiye
4/5The dollar/lira rate rose 13.12%, from 43.0312 lira at the start of the year to 48.6723 lira; the lira cost of imported fuel grew by that much even with the dollar price of the product unchanged.
The share of the interest burden in the budget · Türkiye
4/5In January-August interest payments rose 39.4%, approaching 2 trillion lira; the deficit is 1,308.1 billion lira. The fastest instrument for protecting the primary surplus remains indirect taxation.
Tactical frictiontemporary · eases over time
Uncertainty in the repair timetable weeks
4/5Yaroslavl's governor said the fire had been extinguished, but there is no announced repair timetable for AVT-3; AVT-4 has been under repair since 28 August.
The ban has not been formally announced weeks
3/5The extension was decided at a meeting chaired by Novak, but the government did not announce it formally and Novak's office did not respond to a request for comment; uncertainty over scope and duration persists.
The composition of the price cannot be separated out months
3/5None of the sources consulted states which crude oil level is reflected in the increase; the shares of product premium, exchange rate and tax cannot be separated with publicly available data.
Source divergence on the size of the increase days
2/5Cumhuriyet reported a rise of 4.80 lira a litre and Habertürk 4.62 lira; there are also kuruş differences in city prices, which complicates the pass-through calculation.
Module B
Signal vs Noise
SIGNAL 57% · NOISE 43%
- SIGNAL
The scope of the ban widened from traders to all producers
A ban that in July covered only traders and small refineries came to cover all producers when it was extended to 31 October; that shows the domestic market being given priority at the expense of the export margin.
Hydrocarbon Processing — Russia set to extend diesel export ban until end of October
- SIGNAL
Export volumes fell by more than half in a year
Russia's diesel exports fell below 1 million metric tonnes in June; a year earlier they were roughly 2.5 million tonnes a month. Türkiye and Brazil lost at least 50% of their previous cargo allocations.
- SIGNAL
The exchange rate channel alone produces a double-digit cost increase
The dollar/lira rate was 48.6723 lira at 09.30 on 17 September; a rise of 13.12% on the 43.0312 lira at the start of the year. Even with the dollar price of the product unchanged, the lira cost grew by that much.
Data: USD/TRY ›BloombergHT — Exchange rates, 17 September 2026
- SIGNAL
The interest line in the budget is growing faster than revenue
In January-August interest payments rose 39.4% to approach 2 trillion lira, while expenditure rose 36.8% and revenue 36%; the deficit came to 1,308.1 billion lira.
Ekonomist — Budget deficit passes 1.3 trillion lira in the first 8 months
- NOISE
The number of drones shot down does not measure the effect of the attack
Kyiv Post gave 65, citing Russian officials, and The Moscow Times gave 641 across Russia and Crimea, citing the defence ministry. The two figures have different scopes and neither measures the capacity lost at the refinery.
The Moscow Times — Ukrainian drone attack sparks fire at Yaroslavl oil refinery
- NOISE
The monthly budget surplus is not a sign of fiscal improvement
August posted a surplus of 12.9 billion lira, but the eight-month deficit is 1,308.1 billion lira and personnel spending rose 42.7%; a single monthly surplus reflects a seasonal collection effect.
Alomaliye — Budget posted a 12.9 billion lira surplus in August
- NOISE
A single day's fall in the index cannot be taken as the measure of the shock
The BIST 100 fell 5.54% on 16 September, but the Fed raised its policy rate to the 3.75-4.00% range the same day; the move is a combination of the local energy shock and a global rate decision.
Takvim — Sharp sell-off in the BIST 100, 17 stocks at their lower limit
Module C
Asset-Class and Positioning Implications
| Asset class | Exposure | Transmission channel | H1 | H2 | H3 | Expected | Conviction | Horizon | What to watch |
|---|---|---|---|---|---|---|---|---|---|
| Commodities | Middle distillate product curve | The curtailment of Russian refinery capacity and the widening of the export ban to all producers | ++ | −− | ++ | +0.80 | ●●● | 0–3 months | The divergence of the Mediterranean diesel product premium from crude oil |
| FX | Currencies of energy-importing emerging economies | Pressure of the energy bill on the current account and the exchange rate | −− | + | −− | −1.10 | ●●● | 0–3 months | How close the dollar/lira rate is to the 50 lira threshold |
| Sovereign debt | Türkiye benchmark yield curve | Domestic borrowing costs rising with the budget deficit and the growing interest line | − | + | −− | −0.60 | ●●● | 3–12 months | Türkiye's 10-year benchmark yield |
| Credit | Türkiye sovereign risk premium | The global rate rise and the energy shock loading onto the risk premium at the same time | − | + | −− | −0.60 | ●●● | 3–12 months | The level of Türkiye's five-year CDS |
| Freight & insurance | Product tanker shipping distance | Routes lengthened by the substitution of Russian cargo and tonne-mile demand | ++ | − | ++ | +1.10 | ●●● | 0–3 months | Mediterranean product tanker freight rates |
| Equities | Türkiye banking and leasing indices | Rising domestic yields and the contraction in foreign risk appetite | − | + | −− | −0.60 | ●●● | 0–3 months | The banking index's path relative to the main index |
Triggers
Thresholds to watch
| Indicator | Threshold | Today | What it means |
|---|---|---|---|
| USD/TRY | > 50 | 48.68 | The rate settling above 50 lira enlarges the lira cost of imported fuel enough to require a new round of increases even if the dollar price of the product stays unchanged. |
| Türkiye 10-year yield | > 34 | 32.62 | The benchmark yield passing 34% signals that, with the budget deficit at 1,308.1 billion lira, domestic borrowing costs will produce a second jump in the interest line. |
| Brent crude oil | > 115 | 130.80 | Crude oil passing 115 dollars, loaded on top of cargo scarcity and the exchange rate effect, turns an excise adjustment from a fiscal choice into a necessity. |
Sources
- OilPrice — Russia extends diesel export ban through October
- Hydrocarbon Processing — Russia set to extend diesel export ban until end of October
- United24 Media — Major Russian oil refinery forced to stop processing after deep strike
- Kyiv Post — Rostov airfield and Yaroslavl refinery hit in overnight attack
- The Moscow Times — Ukrainian drone attack sparks fire at Yaroslavl oil refinery
- Cumhuriyet — Diesel prices pass 100 lira, fuel prices on 17 September 2026
- Habertürk — Third fuel price rise in a row, diesel passes 100 lira
- BloombergHT — Exchange rates, 17 September 2026
- Takvim — Sharp sell-off in the BIST 100, 17 stocks at their lower limit
- Alomaliye — Budget posted a 12.9 billion lira surplus in August
- Ekonomist — Budget deficit passes 1.3 trillion lira in the first 8 months of the year
Sourcing and verification rules: methodology · Report an error: contact
Related reports
IGeo-Economics·Analysis·Sub-Saharan Africa
Africa's fuel problem is no longer price but the last mile: the valve, the road and the pump are cut separately
Brent fell from 104.82 dollars on 17 September to 100.05 dollars on 22 September. In the same five days a valve in Libya, a trunk road in Mali and petrol stations in Sudan were cut off; the cheaper barrel touched none of them.
Africa Desk · 22 September 2026 · 9 min
IGeo-Economics·Analysis·Eurasia
Russia's refining loss has stopped being a war statistic and become a monetary policy line: 45% of capacity is out
Both distillation units at the Moscow Refinery burned, and the Kuibyshev and Ufaneftekhim plants were struck on the night of 21–22 September. The Bank of Russia now counts fuel prices within the core inflation dynamic in its rate statement.
Eurasia Desk · 22 September 2026 · 9 min
IVMacro & Debt·Analysis·Türkiye and Its Neighbourhood
Inside Türkiye's rising confidence index: spending is being pulled forward while the energy shock builds up at the producer
Consumer confidence rose to 91.9 in September, its highest since July 2018. Yet the only sub-index above the 100 threshold is the propensity to spend on durable goods; the index of the current financial situation is the only component that fell.
Türkiye & Neighbourhood Desk · 22 September 2026 · 10 min